The short version
Adverse selection happens when one side of a deal knows something relevant about their own risk that the other side can't see, and the terms end up skewed toward exactly the people a seller least wants. An insurer that has to charge everyone the same premium attracts the customers who already know they'll use the coverage and repels the ones who probably won't. A used-car lot where sellers can tell which cars are lemons and buyers can't ends up flooded with lemons, because owners of good cars won't sell at a lemon-adjusted price.
The mechanism doesn't require anyone to lie. Nobody has to commit fraud for it to work. The information gap does the work on its own, and it tends to compound the longer a market runs, because the people who leave first are the ones with the least reason to stay.
The paper that was too obvious to be true
George Akerlof finished the paper that gave this mechanism its name, "The Market for 'Lemons': Quality Uncertainty and the Market Mechanism," in June 1967, while teaching at Berkeley. He sent it first to the American Economic Review. The editor rejected it, explaining, in Akerlof's own later account, that the journal did not publish papers on subjects of such triviality. He sent it next to The Review of Economic Studies, at the encouragement of an editor there who had visited Berkeley while Akerlof was writing the paper. Same verdict: not a subject worth the journal's pages.
A third submission, to the Journal of Political Economy, came back with two detailed referee reports arguing that eggs and other farm goods of uneven quality are already sorted and sold all the time, without any trouble, so the paper's premise couldn't be right. Eggs and used cars do share a category, goods of uneven quality, but not the one property the referees' comparison actually needed from them. A shared category is not the same thing as a shared conclusion: an egg grader can crack a sample from every crate before a sale closes, and a car buyer standing on a dealer's lot generally can't take an engine apart first. Akerlof later summarized what he took to be the reports' real objection this way: if the argument held up, it would mean economics itself worked differently than everyone had assumed it did.
He sent the paper to a fourth journal, the Quarterly Journal of Economics, where it was accepted and published in 1970. Thirty-one years later, in 2001, Akerlof shared the Nobel Prize in Economic Sciences with Michael Spence and Joseph Stiglitz, officially "for their analyses of markets with asymmetric information," the theory that three editors had waved off as too trivial to print.
A state builds Akerlof's exact scenario, then removes half of it
Washington State supplied a real-world test of the mechanism Akerlof had modeled twenty-three years earlier, not deliberately, and not run by economists. State lawmakers built one half of his setup, then, before finishing, tore out the other half.
In 1993, with Democrats controlling the Legislature and the governor's office, Washington passed the Health Services Act, described at the time as the nation's most sweeping state health-care reform law. Its central trade was guaranteed issue: insurers had to sell an individual policy to anyone who applied, regardless of health, at a shared community rate that didn't vary by age or medical history. That was paired with an employer mandate and a planned requirement that every resident carry insurance by 1999. The state insurance commissioner put guaranteed issue and a limited preexisting-condition exclusion into effect starting July 1, 1994, ahead of the rest of the law's original timeline.
Then, after Republicans won control of the state House in the 1994 elections, the 1995 Legislature passed a bill stripping out the employer mandate, the premium price cap, the state insurance-purchasing cooperatives, and the requirement that residents eventually buy coverage. What survived was guaranteed issue and a relaxed version of community rating. Insurers still had to sell a policy to anyone who asked, at close to a flat rate. Nothing required anyone healthy to buy one in the meantime.
What the numbers actually did
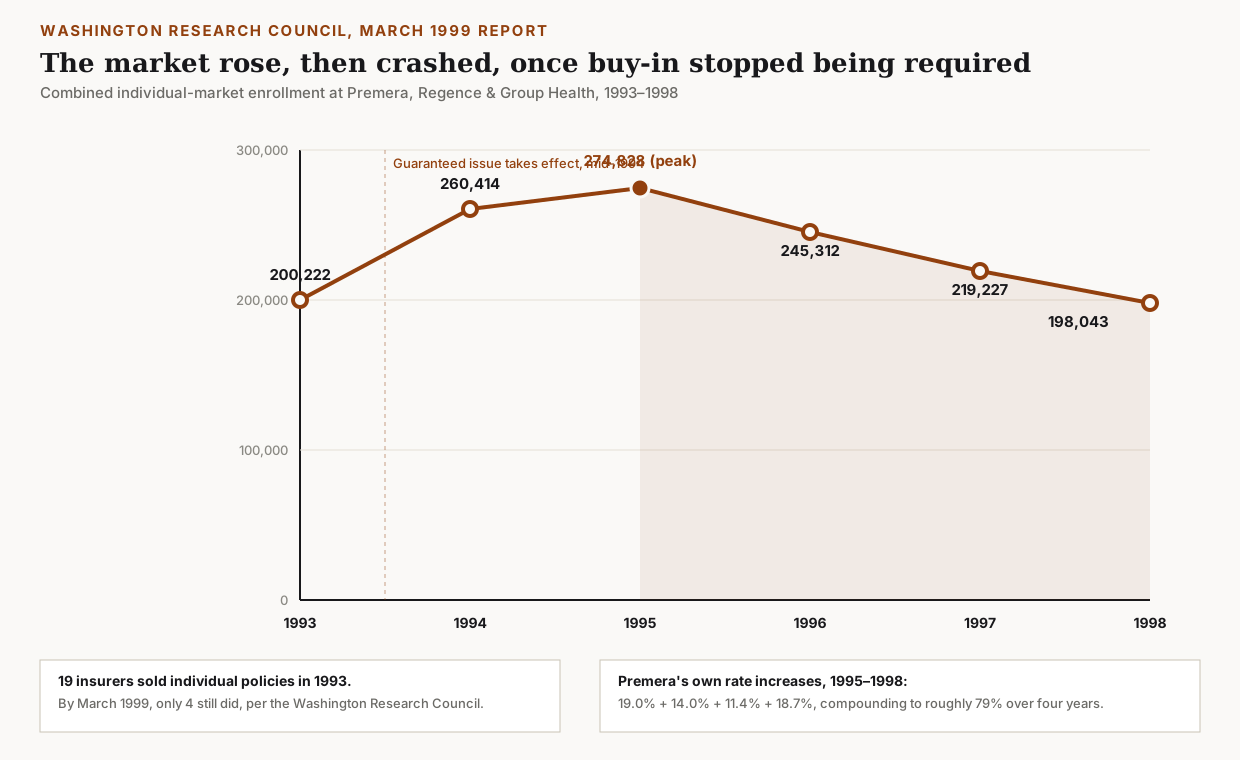
Insurer filings, tracked afterward by the nonpartisan Washington Research Council, show what happened to the individual market once guaranteed issue took effect without a mandate behind it. Combined enrollment at the state's three largest carriers, the companies that became Premera Blue Cross, Regence BlueShield, and Group Health Cooperative, rose from 200,222 in 1993 to a peak of 274,828 in 1995, a jump of roughly 37 percent, as people who'd previously been turned away over preexisting conditions came in. Then it reversed. By 1998, combined enrollment had fallen to 198,043, down about 28 percent from the 1995 peak and back below where it had started five years earlier.
A single before-and-after number can hide the same thing a combined total hides when it's built from two very different subgroups moving in opposite directions: 1993 to 1998, on its own, looks almost like nothing happened, 200,222 enrolled at the start and 198,043 at the end. What actually happened in between was a pool that nearly swallowed itself whole.
Premera's own posted individual-market rate increases for those years were 19.0 percent in 1995, 14.0 percent in 1996, 11.4 percent in 1997, and 18.7 percent in 1998, a run that compounds to roughly 79 percent over four years. By March 1999, only 4 of the 19 insurers that had sold individual policies in Washington in 1993 were still doing so.
One woman's letter, and the pattern behind it
In 1995, a woman in Eastern Washington bought an individual policy from Premera a few months before she gave birth. As soon as the insurer paid her hospital bill, she canceled it, writing to Premera that they would do business again "when we are pregnant." She later bought coverage again for a second pregnancy, and canceled again once that claim was paid. Across both pregnancies she paid $1,807 in premiums; Premera paid out $7,024.68 in her medical bills, according to a Seattle Times account that reviewed the letter.
The state's own data show this wasn't one customer being clever. It was the predictable shape of the whole risk pool. In Premera's individual plan that mirrored the state's Basic Health Plan and included maternity coverage, 80 percent of new adult enrollees in one recent year were women, and of the women who enrolled and had a baby during the year ending September 1997, 73 percent canceled their coverage within the first eight months, and of those who canceled, 15 percent did so the same month they gave birth. Guaranteed issue meant none of them had to wait out a preexisting-condition clock, and nothing required them to keep paying once the bill was covered.
Premera itself put it plainly at a legislative hearing. "They are making reasonable and appropriate personal choices which are available to them," said senior vice president Trae Anderson. "The fault lies with the system we've set up, not with the people who are participating in it."
The fix, and what it cost to get insurers back
By 1998, Premera had stopped accepting new individual applicants altogether, while remaining legally required to keep serving roughly 119,000 existing policyholders. Company officials later said Premera lost $120 million, in today's dollars, on individual coverage before making that call. By mid-1999 the state's other two major carriers, Regence BlueShield and Group Health, had stopped selling new individual policies too. For practical purposes, Washington residents without existing coverage could no longer buy an individual health plan from a private insurer.
Governor Gary Locke spent 1999 negotiating a fix, signed into law in the spring of 2000. It brought insurers back by giving them room the original 1993 law had denied them: they could set their own individual-market rates without the state's standard rate review, make new applicants with health problems wait nine months instead of three before a preexisting condition was covered, and reject up to 8 percent of applicants outright. Rejected applicants could buy coverage through a revived state high-risk pool, subsidized by the same insurers now allowed to turn them away. State Senator Alex Deccio, a Yakima Republican who helped write the compromise, described the logic without dressing it up: "We are in a private-enterprise system."
Where else an information gap gets priced against you
Akerlof's original paper was about used cars, not insurance, but the mechanism travels to any market where one side can see something the other side can't verify. It shows up wherever a warranty, a return policy, or a security deposit exists, because a seller who can't tell a careful buyer from a careless one has to price for the careless one. Dating profiles, freelance marketplaces, and peer-to-peer lending run into the same thing, anywhere a platform lets one side self-report facts the other side has no way to check.
Akerlof's model never required anyone to lie, and neither did the people canceling Premera policies right after their claims cleared, which points to a more useful question than hunting for a liar. Ask who a flat rate, a standardized contract, or a waiting period was actually written to protect, because those terms usually exist because someone upstream had already priced for the buyer they couldn't screen out. A deal that looks unusually generous with no visible catch is often hiding that catch in a clause you haven't read yet.